A teenager can earn good grades, complete household responsibilities, and prepare for a job while still knowing very little about managing money. Financial independence requires practice.
Before leaving home, teen girls should have opportunities to create a budget, use a bank account, compare prices, save for goals, distinguish needs from wants, and experience the consequences of manageable financial decisions. These skills are easier to learn when the amounts are small and supportive adults are still nearby.
Begin With Real Money and a Real Purpose
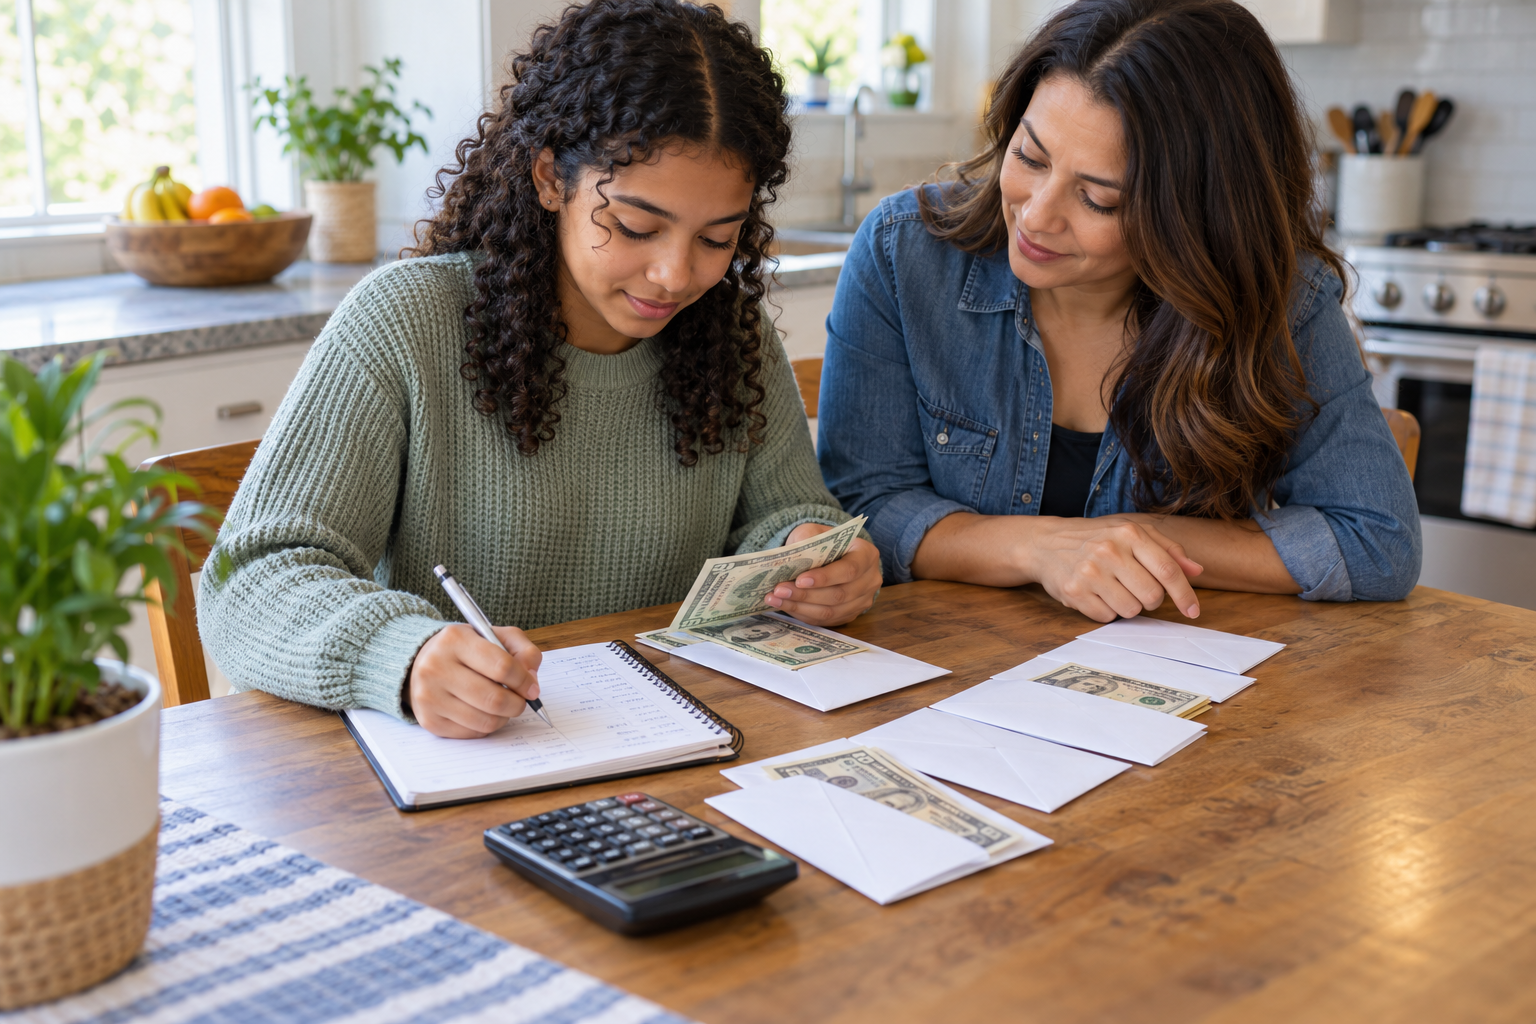
Money lessons become more meaningful when a teenager is responsible for actual decisions. The money might come from a part-time job, babysitting or yardwork, an allowance, gifts, a clothing budget, or money designated for school activities.
The purpose is not to give a teen a large amount. It is to give her enough control to practice planning, choosing, and adjusting. The Consumer Financial Protection Bureau’s resources for teenagers note that teens increasingly earn money and make independent decisions while continuing to benefit from adult guidance and feedback.
Teach the Difference Between Income and Available Money
When a teenager receives $100, she may initially view all $100 as available to spend. A simple plan can divide it into savings, necessary expenses, giving, flexible spending, and a future goal. The percentages can vary; what matters is learning that receiving money and having money available for an immediate purchase are not the same.
Help her track money coming in, expenses, savings, what remains available, and upcoming expenses not yet paid. This is the foundation of budgeting.
A Budget Is a Plan, Not a Punishment
A budget is a plan for using limited money according to what matters most. Start with a short period, such as one week or one month, and compare the plan with what actually happened. A basic plan might include income, required expenses, savings, giving, flexible spending, and a remaining balance.
The FDIC’s Money Smart curriculum for grades 9–12 includes lessons on spending, budgeting, saving, choosing a banking partner, and other financial decisions relevant to teenagers.
Make Needs and Wants More Specific
Some decisions fall clearly into one category. Food is a need; an expensive restaurant meal is usually a want. Clothing is necessary; replacing a usable jacket because a different one is popular may not be.
Help her ask: Do I need this now? Do I already own something that serves the same purpose? Is there a less expensive option? What will I give up if I buy it? Will I still want it tomorrow? Can I afford the ongoing cost, not only the initial price? The objective is not guilt; it is recognizing tradeoffs.
Saving Works Better With a Named Goal
“Save money” is vague. “Save $300 for a used laptop by March” gives a teenager something she can plan. Help her define the amount, target date, what she already has, how much to save each week or month, and which choices might slow the goal.
The CFPB teen-saving guidance recommends tracking spending, comparing financial institutions, and establishing a regular saving habit.
Teach Her How a Bank Account Works
A teenager should understand more than how to tap a debit card. Explain checking and savings accounts, available balances versus pending transactions, debit-card purchases, deposits and withdrawals, direct deposit, statements, overdrafts, ATM charges, fees, interest, password and PIN security, and how to report unfamiliar transactions.
When comparing a bank or credit union, review fees, minimum-balance requirements, ATM access, online features, customer service, and youth accounts. Let her participate and learn how to review activity and ask for help if something looks wrong.
Let Small Financial Mistakes Teach
A teen may spend too much early in the month, forget to plan for an event, or regret an impulsive purchase. When the stakes are manageable, that discomfort can become a useful teacher instead of replacing the money immediately.
Ask what she expected, what happened, which expense she overlooked, what she will do until the next earning period, and how she can change next month’s plan. A small mistake at 16 can be far less costly than the same habit involving rent, credit cards, or car payments at 20.
Explain Digital Spending
Money can feel less real when a purchase requires only a tap. Teach teens to review app subscriptions, free trials, renewals, delivery fees, in-game purchases, peer-to-peer payment apps, buy-now-pay-later offers, and saved card information. A pause—even 24 hours—can help reconsider whether an unplanned purchase fits the budget.
Introduce Borrowing Before She Needs It
Explain interest, loan terms, minimum payments, late fees, credit reports, repayment time, the risks of borrowing for ordinary wants, and why a low monthly payment may still mean a high total cost. This does not require encouraging a teen to open a credit account; compare sample costs and discuss how debt affects future choices.
Connect Money to Everyday Independence
Money management draws on planning ahead, delaying a want, following through, evaluating information, keeping records, protecting private information, adjusting after mistakes, asking for help, and making choices based on priorities.
At Trailhead Girls Academy, budgeting and money management are part of a broader emphasis on practical life skills. Trailhead is a non-therapeutic private boarding school for girls ages 12–18 focused on academics, responsibility, relationships, employment preparation, and increasing independence.
Seven Money Skills to Practice Before Adulthood
- Create and follow a monthly budget.
- Track purchases and compare them with the plan.
- Save consistently for a defined goal.
- Use a checking and savings account.
- Read an account statement.
- Compare prices and delay an unplanned purchase.
- Recover from a small financial mistake without being rescued automatically.
These experiences can be adjusted to her age and circumstances. The essential element is that she participates in the decisions.
Confidence Comes From Practice
Parents do not need to be financial experts to teach useful money habits. Start with ordinary choices: planning grocery costs, comparing products, reviewing a pay stub, dividing a paycheck, or discussing why the family waits before a large purchase.
The goal is not to ensure a teenager never makes a financial mistake. It is to help her recognize one, learn from it, and make a better decision next time. A young woman who knows how to plan, save, use banking tools, and pause before spending is better prepared for the practical freedom of adulthood.
Families can learn more about Trailhead’s approach to independence, explore its academic and vocational opportunities, or contact admissions to discuss their daughter’s goals.